Simplifying IT
for a complex world.
Platform partnerships
- AWS
- Google Cloud
- Microsoft
- Salesforce
ShareRing gives banks and ADIs reusable, privacy-first KYC built to the AUSTRAC AML/CTF requirements and to ISO 27001. Customers verify once through an encrypted vault, your compliance team gets a signed result in seconds, and the cost per onboarding drops by an order of magnitude.
Onboard in seconds. Stay compliant for life.
 ShareRing Me
About a minute the first time. About two seconds at the next institution that asks.
 ShareRing Link
One result per applicant, carrying the fields the workflow asked for.
The problem is not that verification is hard. It is that you are storing personal identity documents to do it: passport copies, government IDs, driver licences. Every document you hold is a liability. The maximum penalty for a serious privacy breach in Australia is $50 million per contravention, and the regulator is suing Optus on the basis of one contravention for each of roughly 9.5 million affected people.
Mid-tier banks burn millions every year on manual verification, document scanning and compliance overhead. Costs climb as regulations tighten.
Document uploads, video calls, manual reviews. Modern banking should be faster, and your competitors already are.
Nearly half your prospects abandon onboarding. They verified once already and expect it to stick.
A breach costs millions. The only identity document that cannot leak from your servers is the one you never stored.
Your customer verifies once and carries that credential in their app. They present it to any business in the network: passport scan done, AML check done. They never repeat it, and you never hold it.
The three pieces
Reusable KYC built to the AML/CTF Act 2006 and AUSTRAC enrolment requirements for Australian banks and ADIs, with information security controls and privacy-by-design built to GDPR, CCPA and the Australian Privacy Principles.
What that means in practice
Real deployments. Real results. See how this solution performs with actual clients.
Singapore’s first licensed crowdfunding platform: over $20 million raised across 30+ campaigns and 1,800+ verified investors, on two-tier KYC. Zero personal identity documents stored on FundedHere servers.
Digital identity verification deployed for a national bank.
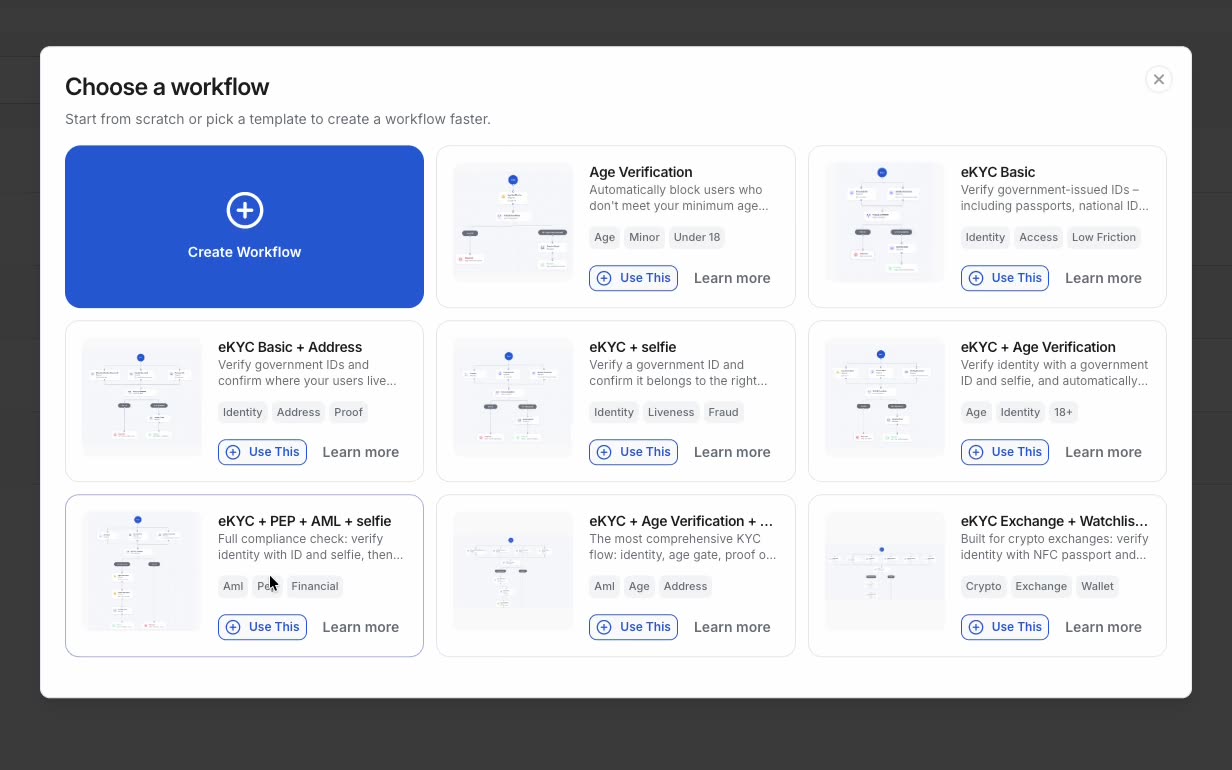
The e-KYC Medium shape, which is what an ADI onboarding actually needs. Two documents captured in parallel, a third where the policy names one, and the watchlist screen held back until the cheap checks have already eliminated the failures.
age_verification
Over 18.
identity_document
Passport, NFC read.
identity_document
Licence or ID card, captured at the same time.
other_document
A third document where the policy names one. Two forms of ID, read and matched, not a bill in a drawer.
if_else
Age and every document valid.
personal_info
Full name and country, for the screen that follows.
watchlist
Sanctions, PEP and adverse media.
delivery_http
The full verification payload, signed, to your core system.
end_ok
A verified customer, and no document left on your servers.
Only the watchlist screen is billable, and it runs on the customers who already passed. That is the difference between $5M a year and a fraction of it.
Longer pieces from The Privacy Stack on the regulation, the cost and the mechanics behind this page.
The average KYC review costs $2,598 per corporate client. Banks spend $60 million a year on compliance. Reusable…
6 Apr 2026Australian privacy penalties jumped from $2.22 million to $50 million overnight. Here is what that means for any…
30 Mar 2026Photocopying a passport is not KYC. It does not confirm the document is genuine, does not screen sanctions lists, and…
ShareRing gives you enterprise-grade identity verification without building it yourself.